

No, it looks like they know. I will return to the 80% funded ratio myth towards the end of this post.
24 July 2026, Bond Buyer: Pension funding looks great, but continued success is unclear, by Colin Royal
On the surface, public pension funds are having a great year so far.
A recent report for the Equable Institute showed that pension funds are at their best funded status since the 2008 financial crisis’ market bottom. States are meeting their required contributions, and 15-year-old amortization schedules are starting to outpace interest on pension debt.
The national funded ratio is at its best since 2009 at 85%, the gap between funds’ assets and liabilities is $210 billion less than 2025, and the employer contribution rate reached a historic high of 31.83% — three times more than 2001, according to Equable Institute’s 2026 pension report.
….
"I would caution anyone just to look at that funding ratio because that is far from telling the story," Bond Buyer Intelligence Analyst Jeff Lipton said. "I don't mean to say that you know an 85% funding ratio is insignificant, but… you have to look under the hood. You have to look at the underlying assumptions."
Okay, we will get back to that stuff in a bit, but let’s look at this Equable Institute report.
Equable Institute Report on Public Pensions, 2026
Link to the report summary: https://equable.org/report/state-of-pensions-2026/
Full report: https://equable.org/wp-content/uploads/2026/07/Equable-Institute_State-of-Pensions-2026_Final_062226.pdf
Key exhibit: a choropleth of the funded ratios by state.
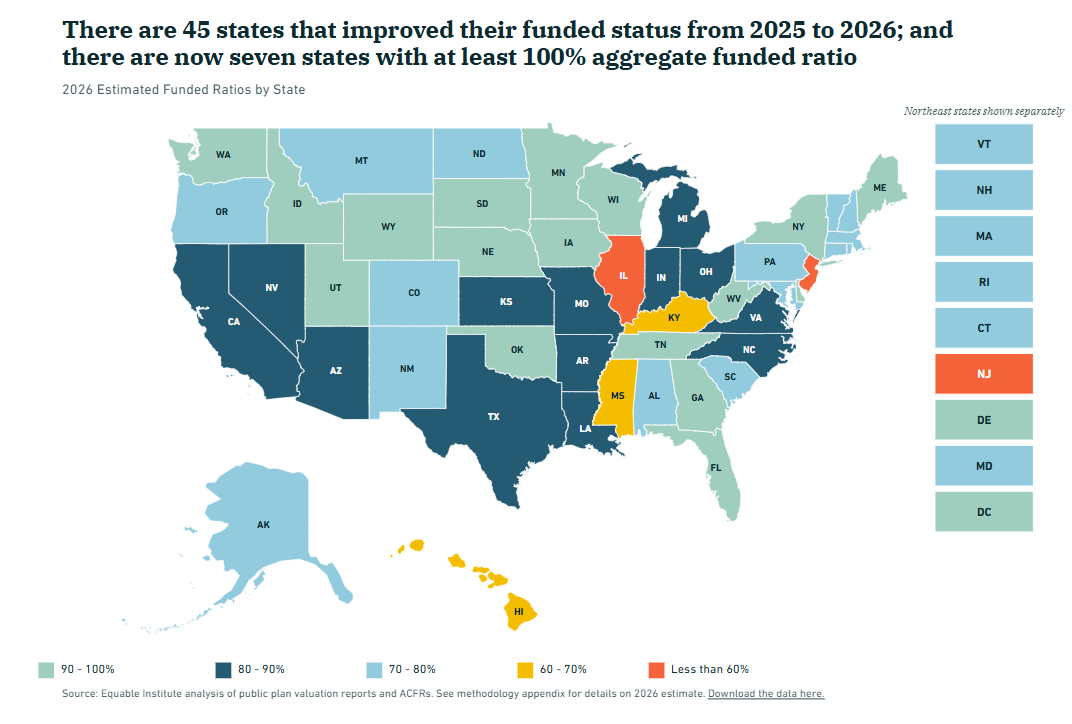
I don’t like their choice of colors, because the highest-funded states go over 100% (and they can), and the light blue seems “less good” visually than the heavy blue. Not a good choice, guys.
For the states in danger, though, those are good choices for colors. Illinois and New Jersey really “pop”.
This is what Equable has to say:
The following key facts provide insight into what’s driving improvements in funded status as well the structural risks pension plans face going forward.
Funded Status: The 85.0% projected national average is up from 81.2% in 2025; 41.5% of plans are now within Resilient funded status.
Unfunded Liabilities: The $1.13 trillion total shortfall is only down $210 billion versus 2009 in absolute dollars.
Contributions: 31.83% of payroll is a new historic high employer contribution rate; pension debt repayments are 70.4% of employer costs.
Investment Returns: The 9.37% average return projected for 2026 beat the 6.8% target for the fourth straight year; the 10-year rolling average is now 8.69%.
Valuation Risk: 27.1% of public pension assets are valuation-priced versus market-priced, which is up compared to a five-year rolling average.
A.I. Investment Dependence: Pension funds have at least 8% to 10% of assets invested in A.I.-related companies; the actual number is certainly higher after factoring in private equity and money with external asset managers.
Is Popularity of A.I. Companies a Systemic Investment Risk Specifically for Public Pensions?
Here is my question on the last item:
How much of the current market assets are A.I.-related companies to begin with?
Equable calls it a systemic risk.
But if A.I.-related companies currently make up a lot of the NYSE/NASDAQ, wouldn’t that be a systemic risk for the entire stock market?
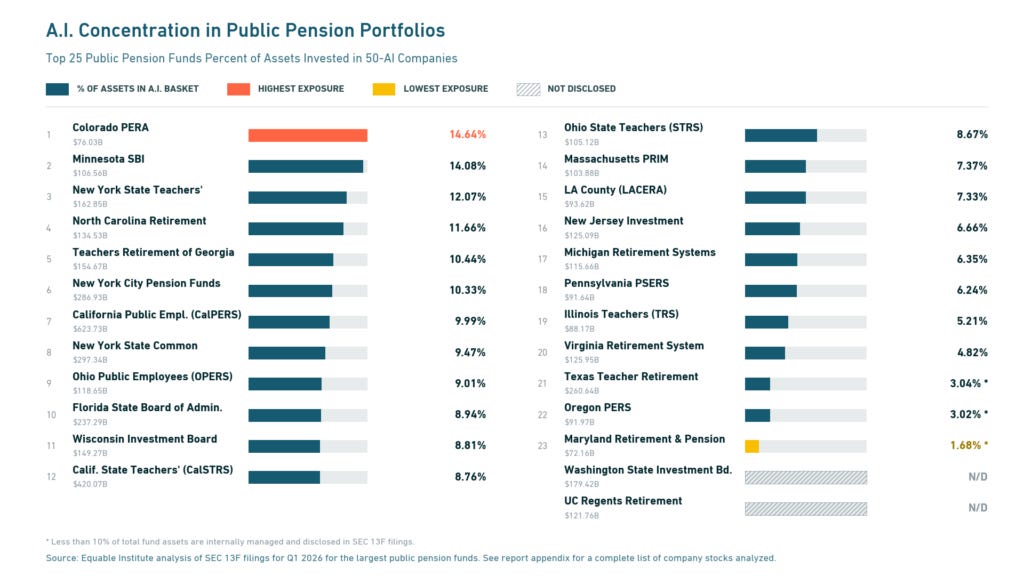
News Flash: Public Pensions Are Not Special In Their Investments
I asked my “research assistant” Gemini what it thought, and this is the table it gave me:
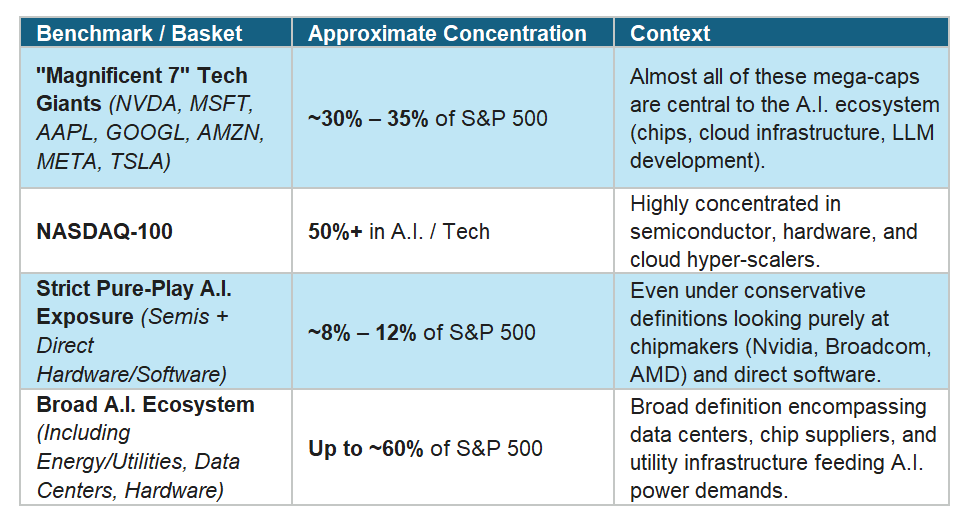
Look at that third row.
Basically, you’re saying public pensions are exposed to A.I. companies at the same amount as the general stock market.
This is how Gemini put it:
Key Takeaways for Your Post
It’s a Market Risk, Not a Unique Pension Risk: If public pension funds hold 8% to 10% of their total asset portfolio (which includes bonds, real estate, private equity, and cash) in A.I.-related companies, that is largely a mathematical byproduct of holding standard U.S. index funds or large-cap equities.
Underweighting the Mega-Caps: Because pensions diversify across fixed income, real estate, and private assets, an 8–10% total portfolio allocation to A.I. means their equity sleeves are likely tracking standard market weight—or even tilting conservative compared to holding a plain S&P 500 index fund.
Systemic vs. Specific: Calling 8–10% a “systemic risk” for pensions conflates portfolio-specific concentration with macro market valuation risk. If A.I. equities experience a sharp correction, the whole stock market pulls back—pensions wouldn’t be uniquely exposed compared to any other institutional or retail index investor.
The way I put it: there’s nothing particularly special about public pension investing.
AI companies are what’s hot right now. They have 8-10% of market cap, it seems, depending on how you define “AI companies”.
Oh, by the
The market is exposed to whatever’s hot being volatile. That’s what happens.
This happens to any portfolio if you don’t rebalance it periodically. Whatever’s hot grows in market cap and gets overrepresented in the portfolio. One can question whether pension funds should try being countercyclical in their investing, and weight their sectors different from the market. That might be wise for them.
If it turns out that hot thing is an evanescent bubble which subsequently pops…
Sure Liabilities, Unsure Assets?
…here’s key graph from earlier in the Equable report:
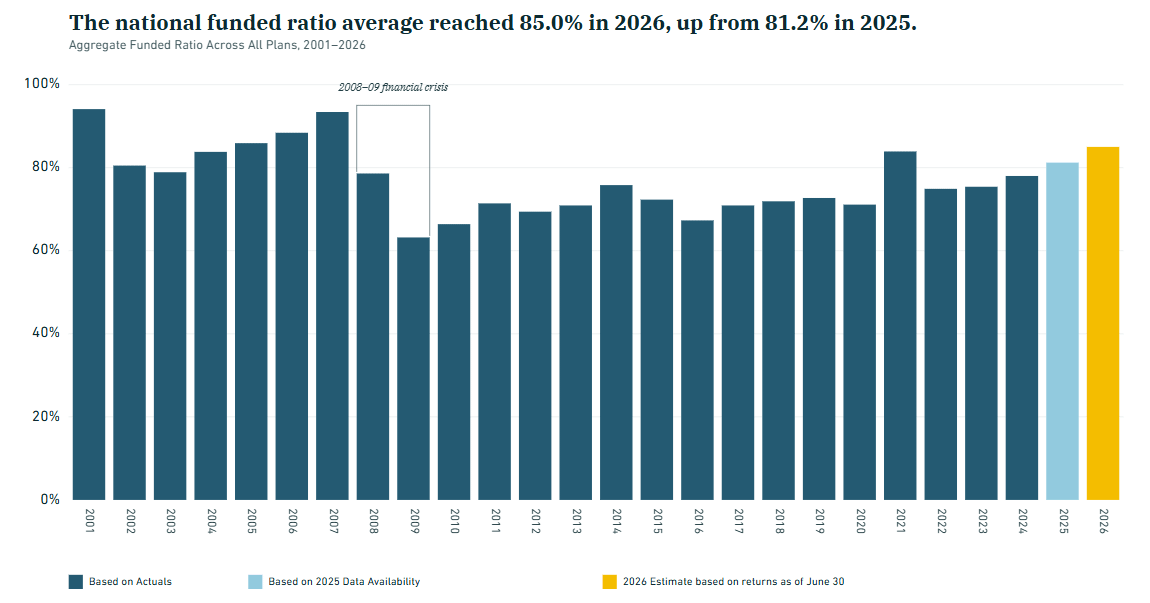
Check out what happened to the funded ratio from 2007 to 2009. It fell from about 93% down to 63% — 30 percentage points — in TWO YEARS.
Mind you, this happened to everybody in the stock market at the time, pretty much.
Maybe public pensions will get back to 93% fundedness (ha ha) by 2029. Twenty years to get back to near-full-fundedness? How precarious are these systems?
But that’s Randazzo’s point (the person doing the Equable Institute reports). Let’s jump back to the Bond Buyer piece:
The current evaluation of pensions is based on pensions being able to pay 85% of future benefits, which depends on public plans averaging a 6.9% rate of return every year in the future, Randazzo said.
“So, because we’re taking all those future benefit payments, we’re saying we’re going to pay all those in the future, and we’re going to use today’s assets, and they’re going to keep growing,” he said. “And the average assumption for all those pension plans is that they’re going to earn a 6.9% rate of return. That has roughly a 50/50 chance of being true.”
Randazzo explained how if public plans operated at 100% they’d be able to incur a few years of market downturns; however, operating at 85% two bad years “could change the whole trajectory of this improvement.”
I added that bolding there.
We saw what the two bad years of the financial crisis did about 20 years ago.
“Valuation Risk” in the Assets
I liked this focus in the report. “Valuation risk” is more helpful than simply saying “alternative assets”.
Let’s see what the Equable report says about this risk, and let me comment:
“Valuation risk” is the risk that the value of pension fund assets as reported to them is inaccurate (e.g., understating or overstating the actual value) because the asset pricing method used is based on valuation models as opposed to market-based prices.
This is important because:
If asset values are overstated today, then that means reported funding levels are overstated. This in turn can lead to lower-than-appropriate contribution rates, which will mean larger unfunded liabilities in the future than if assets were more accurately priced.
Overstated pension asset values can also lead to other policy decisions that could influence future funded status, such as raising the value of benefits or having lower political priority for supplemental funding to pay down unfunded liabilities faster than planned.
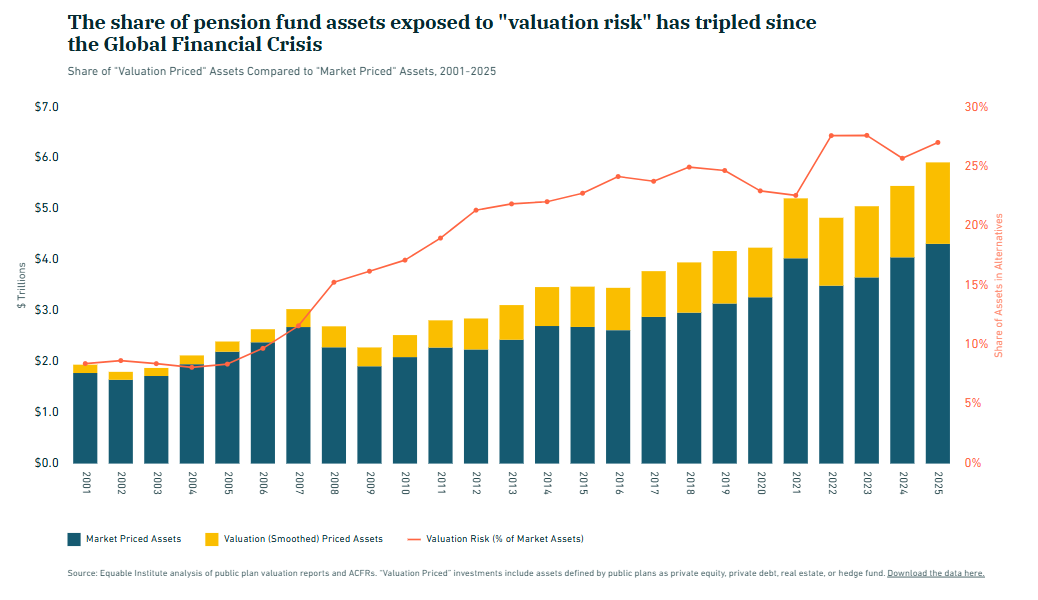
Some asset types there are no “market prices” for. They have to come up with some kind of value — “mark it zero” is also not appropriate…
[insert Big Lebowski gif]
But we’ve seen some hideous outcomes when public pensions don’t have appropriate oversight in the area of “alternative assets”. The outcomes are not necessarily any better than in the public realm when the economy hits a rough patch.
Setting Valuation Assumptions…They’re Linked to the Unfunded Liabilities
So here’s the deal: the funded ratio measures current assets against the actuarial present value of benefits earned thus far. There are a lot of assumptions baked into the valuation of some of those assets and definitely into the valuation of the benefits.
It’s often brought up that these plans are not closed systems (usually) — there will be future participants and future contributions made… but also future benefits accrued.
Each measurement period, you’ve got to build up the value of the benefits again, looking at what’s changed since the last time you measured the pension liability. That’s why my favorite exhibit in actuarial reports is the roll-up of valuations between periods (this exists for insurance liabilities, too — we call it the analysis of change in reserves).
The Equable Institute report recognizes all the above, and even does some of the roll-up kind of analysis:
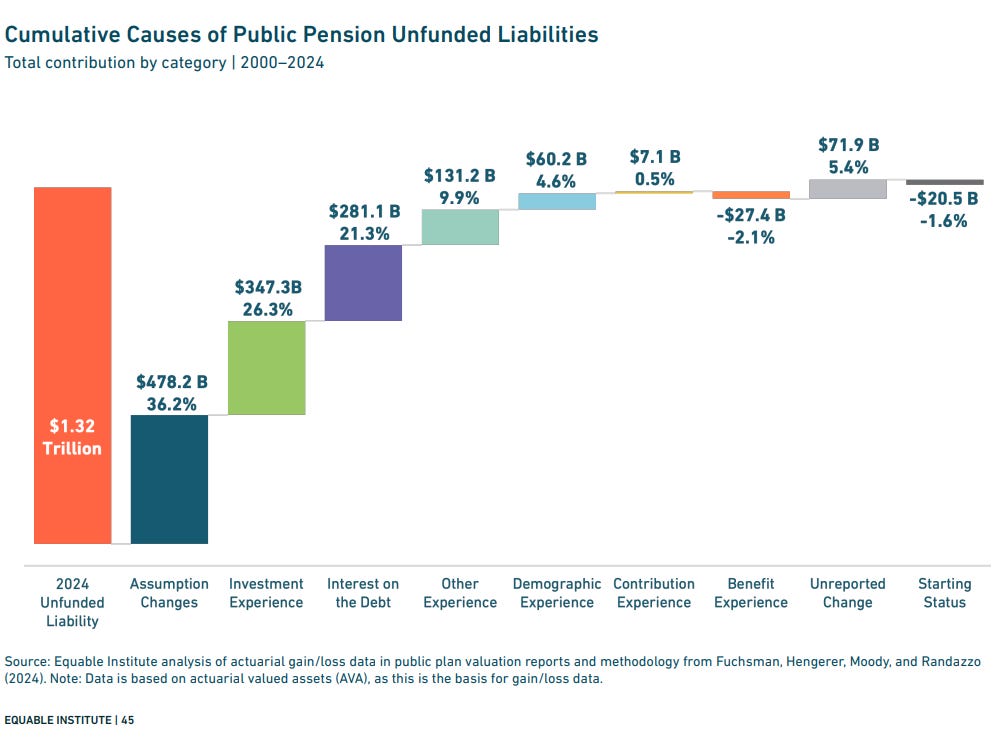
Note that “contribution experience” made almost no difference, but “interest on the debt” made 21.3% of the change — but that’s because the contributions were insufficient to cover the interest accrued on the pension debt.
But here’s the deal about the “interest on the debt” — the states/localities are the ones who decide what interest is “charged” on the unfunded liabilities, by setting the valuation assumptions.
So if they want less interest “charged” on the pension liabilities, they have to reduce the valuation interest rate… which increases the pension liability valuation.
Those assumption changes increases? A lot of that is from dropping valuation interest rates over the years. (Which is the same at the investment targets).
So… the assumption changes, the investment experience, and interest on the debt — all three of those things are basically all linked. And those three together are almost the entire explanation for the increase in unfunded liabilities.
Which is what Equable Institute said on slide 42.
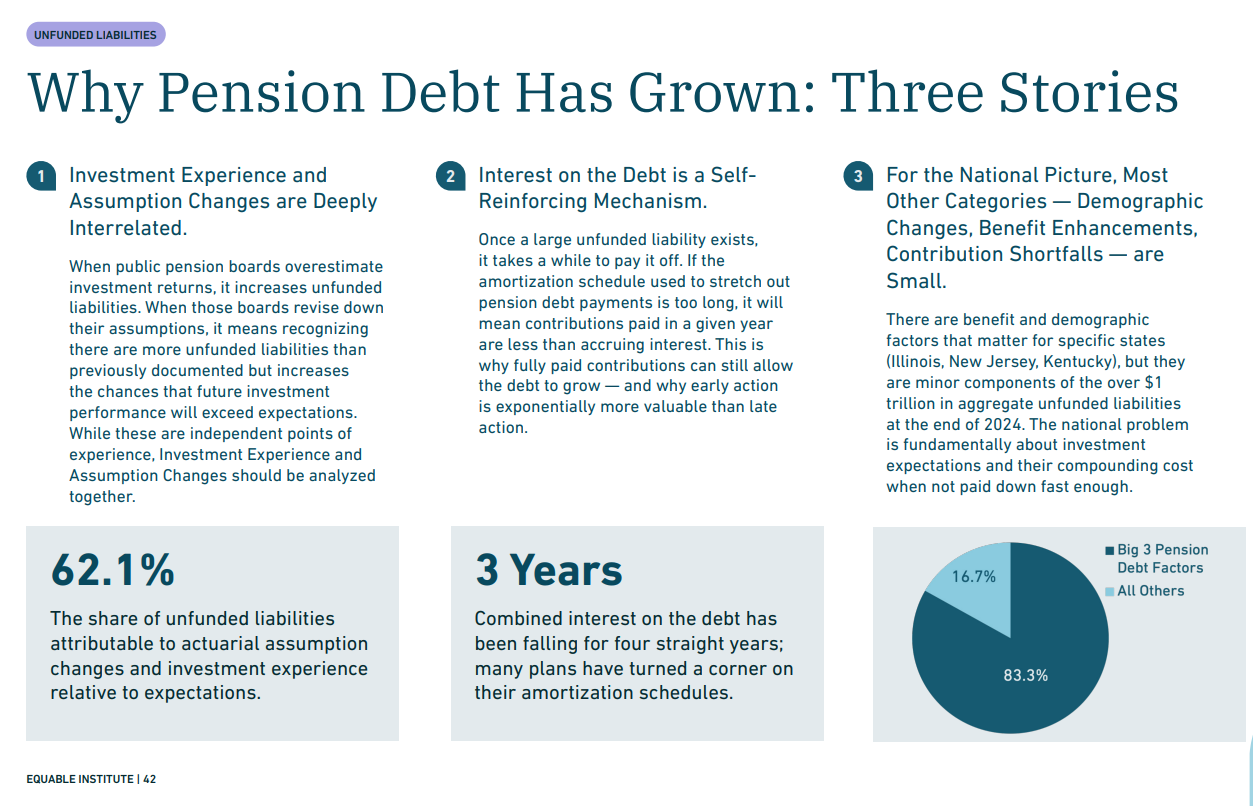
The sooner one acknowledges reality, the better.
The Same Awful Funded Ratios Can Mean Different Things
Here is an ugly reality, from the Equable Institute, in comparing the funded ratios against the various GDPs of the states:
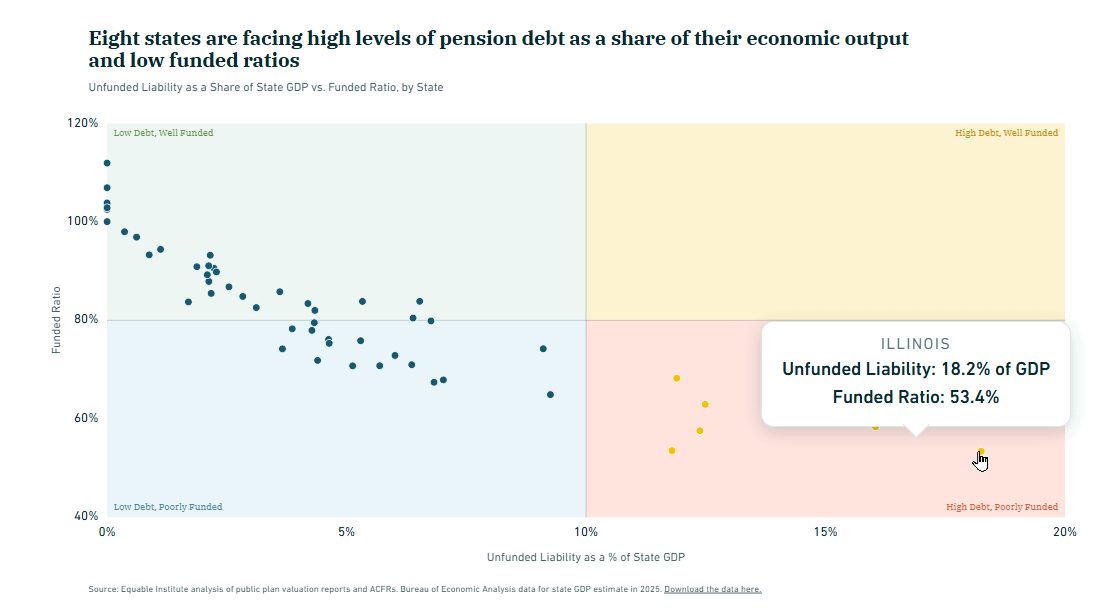
Yes, I highlighted Illinois, in the worst position.
You may be wondering about New Jersey, with about the same funded ratio — but the unfunded liability is at 11.8% GDP. That makes a bit of a difference versus 18.2% GDP in terms of being able to dig out of that hole.
“But we don’t have to pay the pensions all at once!”
Yeah, and that was the unfunded pension measured as of that year, against the state’s domestic product. And that was measured assuming people retire later, at their retirement ages. It’s already baked into the valuation.
The assumption is that people continue to accrue benefits, and that Illinois continues to shortchange contributions on its state pensions, so the liability continues to grow. That’s the unfunded liability already. It will likely get worse, given how Illinois behaves.
Jumping over to my favorite pension data source, the Public Plans Database, here is Illinois’s “required” contribution pattern (not that it ever makes these contributions):
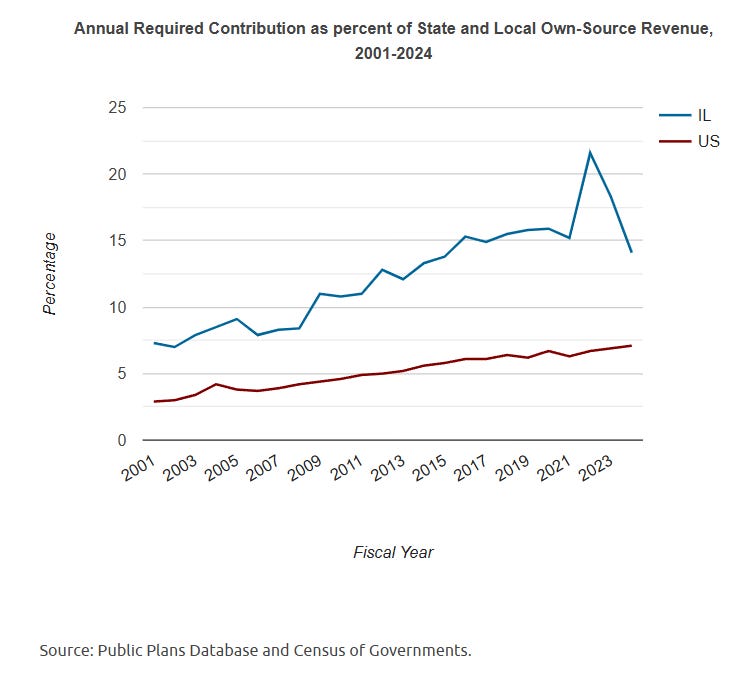
Compare against the U.S. average overall. Yeah.
This is how the New Jersey graph contrasts:
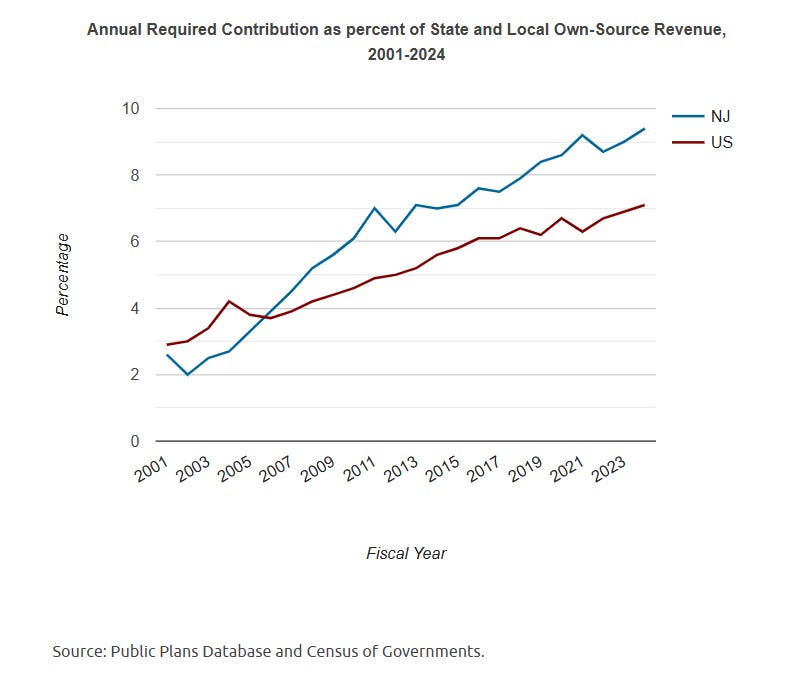
Compare the vertical axes. The max for the NJ graph is at 10% of state and local own-source revenue.
For Illinois, it’s over 20%. Again, Illinois has never made its full contributions for its state pensions (I’m not counting IMRF).
New Jersey has rarely made the full contributions, but sometimes has. That’s the difference.
Back to the Classics: the 80% Funded Ratio Myth
The last time I wrote about this was in 2020, but it seems the American Academy of Actuaries did update their public issue brief in October 2021: The 80% Pension Funding Myth
Financial entities, regulatory bodies, governments and media have all cited an 80% funded ratio1 as a basis for whether a pension plan is “healthy” or “actuarially sound.” The frequency and persistence of these citations potentially lends credibility to a myth that an 80% “standard” is appropriate. This issue brief debunks that myth and clarifies how a pension plan funded ratio relates to the general idea of soundness or health of a pension plan or system. While the funded ratio may be a useful measure, understanding the health or soundness of a pension plan cannot be reduced to a single measure or benchmark at a single point in time. Instead, actuaries evaluate pension plans based on the strategy in place to address all of their unfunded liabilities over an appropriate time frame.
Heh, it looks like they found references even after I stopped writing much about this:
Northwest Indiana Times, Dan Carden, “Indiana grows public pension funds despite market volatility from COVID-19,” September 23, 2020. “Prepaid pension programs generally are considered financially healthy when they are at or above 80% funded.”
….
Florida Politics, Kimberlie Prior, “Senate Bill 84 is fearmongering,” March 18, 2021. “And while a pension fund can achieve 100% funded status, it is not the only, or even the most important measure of the plan’s health. For this reason, it has been a standard actuarial practice to use the 80% funded benchmark as one important measure of the plan’s financial health and an acceptable guideline. FRS is 82% funded.
As we actuaries say: No, it is not standard actuarial practice. It is not “healthy” or anything when a plan is 80% funded.
I kept a spreadsheet of the 80% funded myth hall of fame:

I kept it going 2014-2020, and had a few stragglers afterwards. I still have the news alert, but haven’t really gotten anything but false alarms.
In my last real post on the matter, September 2020, I assumed the myth would be dead:


You can see that the stories have died away.
But why has the myth mainly disappeared from articles about public pensions?
At the end of 2019, I noticed the stories were dying off.
As much as I’d love to take credit for this trend, I know this is not the case. As I said in December 2019:
But let me be realistic: almost definitely this is being driven by stagnating funded ratios, where 80% is aspirational.
Various officials and politicians pointed to 80% when funded ratios were bobbing around that level.
Then some moved the goalposts to 70%. (and by “some”, I mean Dean Baker. And Fitch Ratings, kind of but not really.)
But once you start dipping below 70%, it is really tough to get even the vaguely numerate to believe that 60% or 50% is a perfectly peachy funded ratio. People know that’s a failing grade in school. 80% might be a B – that sounds good. 60% is a D… and 50% is F.
But would the myth come back now that the average is back to 85%?
I’m not sure.
Because not all funded ratios are equal, as mentioned earlier.
The contribution amounts have been climbing, the asset mixes are getting more risky, and it’s getting to be more of a reach to argue that everything is just peachy.
“Healthy”
When the “health influencers” are weirdos like Bryan Johnson, alluding to “healthy” is probably not what you want to do.
Older 80% Funded Ratio Posts
December 2014: 80 Percent Pension Funding Hall of Shame: Experts Say…. — I notice the weasel words of “experts say” rather than naming a specific source.
January 2015: 80 Percent Funding Hall of Shame: Oh THOSE Experts Say – I catch some groups/people being specifically named as sources of the myth, and I noticed Dean Baker moving the goalposts down to 70%.
September 2017: A New Category for the Public Pension Hall of Shame: Never Fully-Funders.
December 2017: Let’s Ring Out the Year with the 80 Percent Funders! – A general roundup, complete with animated gifs!
March 2018: Two Awful Tastes That Go Great Together: Pension Obligation Bonds and 80% Funding Myth. POBs are another big theme I have, but this one stood out because something supposedly said by an actuary:
I am extremely suspicious about the unnamed actuaries who supposedly want to see the pension funded at 75 percent or more.
If an actuary mentioned 75% at all, they may have been referring to what the credit rating agencies are looking for, when considering municipal credit ratings. Whether they should be happy with only a 75% funded ratio after so many years of a rising stock market…. well, I’m not at a credit rating agency.
Yeah, I’m not at a credit rating agency.
To round this out, an April Fools 2015 post from me, rerun in 2025: 80 Percent Funding Hall of AWESOME: Experts Say….
EVERYTHING IS AWESOME!
EVERYTHING IS COOL AT 80 PERCENT
…and more. You have to see to believe…
Public Pension Classic: 80 Percent Funding Hall of AWESOME!

I will have the March 2025 pension round-up later, but for today, I thought I’d replay the STUMP post from this date in 2015, as it was so enjoyable!
Nice post, though I wish you (and Equable and others) would point out that not only are reported asset values almost certainly overstated, but the liabilities are most definitely significantly understated - probably a bigger problem than the former. 85% is probably more like 65-70% when one stops pretending that fundamental principles of finance somehow don't apply to the valuation of pension liabilities.
Other than the assets and liabilities, though, everything's fine.
When one sees "think tanks" that probably know better continue to ignore this issue in what appear to be comprehensive (or at least very long) analyses, one must wonder what source of funding or influence or other benefit to them would be at risk if they addressed the issue honestly instead of utterly ignoring it. They're not doing enough thinking in their pension finance tank.
Kudos to Oliver Giesecke and Hoover for being virtually alone in honestly examining this aspect of public pension funded status: https://publicpension.stanford.edu/.