

Let me round up the latest “discourse” on the “way out” for Chicago pensions.
But first — where the pensions stand.
Chicago Pension Debt: Up Up Up!
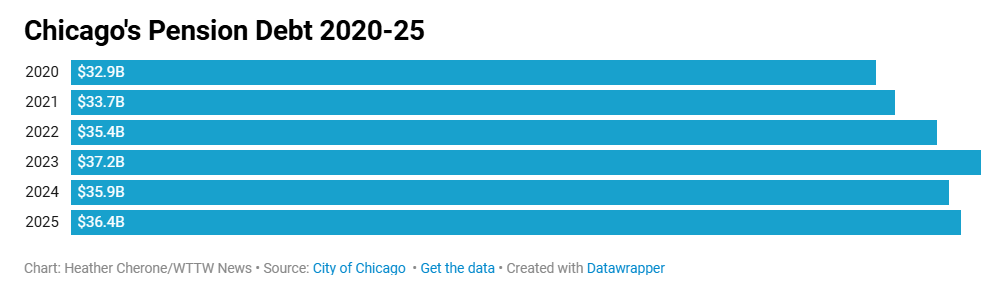
6 July 2026, WTTW: Chicago’s Pension Debt Increased in 2025 to $36.4B: City Analysis
Chicago’s pension debt rose by approximately $500 million in 2025, according to the city’s audited annual financial report, with the amount the city owes to its four pension funds hitting $36.4 billion.
In all, Chicago owed 1.4% more to its four employee pension funds representing police officers, firefighters, municipal employees and laborers at the end of 2025 than it did at the end of 2024, according to Chicago’s 2025 Annual Comprehensive Financial Report.
Chicago’s pension debt has grown by nearly 11% since 2020, adding approximately $3.5 billion to the city’s debt, records show.
One of the items in the ACFR (Annual Comprehensive Financial Report) is the change in the pension liabilities, year-over-year — and I was wondering how much the pension sweeteners affected the pension debt mentioned above.
For reference to the pension sweeteners, go here: 4 Aug 2025 — Chicago Pension Artificial Sweeteners
I went to the 2025 ACFR, and what was cool is they had an Ask a Question feature (no doubt, AI-driven):
And, unlike what I thought would happen, which is give me some LLM-like answer, what happened is it took me to the place in the ACFR itself where the answer existed!
THANK YOU!
Here is the answer:
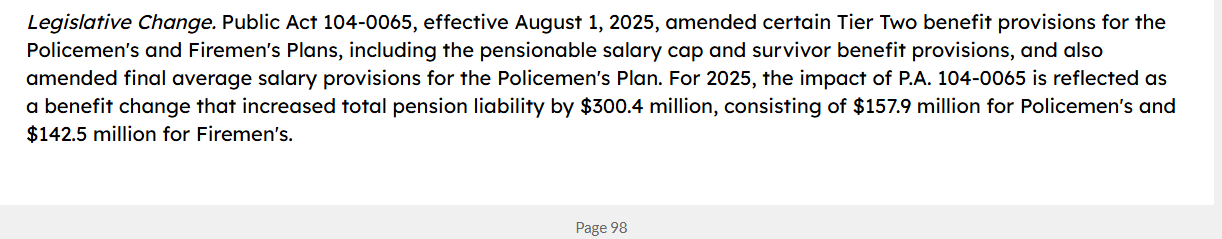
Let me make it easy: the answer is YES.
Policemen’s:
$157.9 million impact in 2025 reporting.
out of a total pension liability reported of $18.9 billion
Firemen’s:
$142.5 million impact
out of a total pension liability of $8.0 billion
The issue with the policemen’s and firemen’s funds is that they are already grossly underfunded. It doesn’t help to add to the liability for those, even if the additions are small compared to the total liabilities.
From the WTTW article:
The fund designed to pay pensions to Chicago’s police officers is just 25.5% funded, while the fund that pays the pensions of the city’s firefighters is 25.2% funded, according to the city’s annual financial report.
The laborers’ fund has the highest funded level, at 44.1%, while the fund that pays pensions to municipal workers is 28.2% funded, according to the report.
These are not great numbers.
I noted that when Johnson became mayor: 15 May 2023 — Did New Chicago Mayor Brandon Johnson Inherit The Worst City Pensions in the Country? [UPDATE AND SPOILER: THE ANSWER IS YES. YES, HE DID.]
We’ve got the numbers: Chicago was in a bad way when Johnson became mayor. The Illinois governor did not help when he signed a pension sweetener into law last year.
The Civic Federation put out a statement in response: [emphasis added]
CHICAGO — The City of Chicago’s 2025 Annual Comprehensive Financial Report confirms that the 2025 public safety pension legislation enacted by Illinois in August 2025 will substantially increase the City’s long-term pension costs. Updated actuarial valuations project that required City contributions to the Police and Fire pension funds will increase by approximately $8.4 billion between 2025 and 2055, or $1.7 billion on a present value basis.
During the consideration of this legislation, the Civic Federation cautioned that increasing pension benefits without providing a dedicated funding source would create significant long-term fiscal pressures for the City. We are now able to see those long-term impacts. This outcome underscores the importance of fully evaluating the downstream fiscal implications of State legislation that imposes new financial obligations on local governments. Pension and other policy changes should be accompanied by sustainable funding plans so that local governments can meet new obligations without further straining future budgets or reducing resources available for essential public services.
The pension sweeteners were going to get passed and signed, no matter what numbers were slapped on there. And it didn’t really matter what numbers were there — those funds were already deeply underfunded when that bill was put together, forget about when passed and signed.
Oh well, “too late”.
But not too late for all the pensions to run into failure.
Whoopsie.
Austin Berg: Hey Chicago, You’re Screwed - Let’s Try Over from Zero
Okay, Austin may not agree with how I’m characterizing the following:
I’m a New Yorker, so I am more blunt… and I would like Chicago to be a really big warning to those in New York. As in, HEY DON’T DO WHAT THEY’RE DOING.
And yes, I like comparing Chicago and New York…. because I much prefer NYC. (I just deleted a huge tangent. De gustibus and all that.)
Keeping to the theme of public finance, at least NYC got its ass kicked by Ford back in the 1970s, and while Mamdani is trying to reverse some hard-learned lessons right now, I have a feeling somebody is going to get learned some hard lessons really hard. Capiche?
Let me jump to 13:30 in the video where Berg talks about Chapter 9 (municipal bankruptcy). [using YouTube transcript, lightly edited]
13:34
Interviewer: Um is it fair to call chapter 9 your release valve?
Austin: So currently Chicago is the only big
city among the top 15 in America that cannot when they have liabilities like
this go to a bankruptcy judge and say I need debt relief. Help me renegotiate this. That’s not a tool that we have at our disposal in Chicago.
….
13:59
so you might be familiar with Detroit is the most prominent example of a city that went through chapter 9 bankruptcy that was over a decade ago
Detroit today has a better credit rating than the city of Chicago wa so it it can be very helpful for a city
but it’s also extraordinarily painful and extreme
14:18
okay so chapter 9 should be a very very last resort and what we need in Illinois is a
14:25
framework for distressed cities, okay, which we don’t have. Governance is just by the seat of our
14:31
pants, it seems like, especially in Springfield and especially in Chicago. And what a framework for distressed cities would do is say, here’s an early
14:39
warning system, almost like a weather like a like an extreme weather early warning system where we’re taking stock
Because of Illinois state law, Chicago cannot unilaterally declare municipal bankruptcy (Chapter 9). It’s a lot more than “distressed cities”, and I cut off the transcript before he talks about Harvey, Illinois, which is a completely screwed-up situation. Liz Farmer wrote about Harvey over several years at Governing; here are a couple pieces:
2014: The SEC Halts Fraudulent Bond Offerings in Harvey, Illinois
2018: This Illinois Town Is on the Brink of Bankruptcy. How Many Will Follow?
Something very special went on in Harvey, and no, other Illinois towns didn’t follow it for very good reason… because they didn’t do what went on in Harvey.
That Chicago cannot file for Chapter 9 bankruptcy in federal court without the permission of the Illinois legislature is actually fine, I think. Yes, I understand that essentially means, given the politics of the situation, that Chicago is barred from Chapter 9. But it does not mean that it is completely off the table. The politics of the Illinois legislature is not a law of nature; it can change.
So can the state constitution.
If you are not a finance person (and some people who are in finance) do not necessarily understand what Chapter 9 bankruptcy can and cannot do.
It’s a legal process in federal court. It doesn’t cause money to appear from nowhere. It doesn’t cause art that a city doesn’t own to come into being — people get confused when proposing “Hey, let’s have a Grand Bargain like Detroit had in its bankruptcy!”, forgetting that Detroit for some odd reason owned art it could hold ransom. As far as I know, Chicago the city owns no such art.
Chapter 9 bankruptcy, i.e., municipal bankruptcy, is not the same thing as bankruptcy for an individual or a company. The city is not going to liquidate. Creditors know that. The creditors have limits on what they’re going to get — they will not necessarily get zeroed out (but some might).
Some creditors can argue that other creditors shouldn’t get 100% of what they were promised in bankruptcy proceedings. That is, pension participants shouldn’t necessarily get 100% of what they were promised when a municipality goes through Chapter 9 bankruptcy.
That’s exactly what happened in the Detroit bankruptcy.
Various non-participants in the Detroit bankruptcy filed pleadings, trying to prevent pension cuts. They were unsuccessful.
Because of the Grand Bargain, the pension cuts were less than they could have been:
A critical component of Detroit’s plan to exit bankruptcy in December 2014 was coined the “Grand Bargain.” Its goals were to prohibit the sale of artwork from the city-owned Detroit Institute of Arts (DIA) to pay off the city’s massive debt, to preserve city pensions, and to satisfy creditors. Under the terms of the bargain, $816 million was donated by multiple foundations (consolidated into the Foundation for Detroit’s Future), Detroit Institute of Arts donors, and the State of Michigan. The funds were to be dispersed over twenty years to the General Retirement System and the Police and Fire Retirement System to help ameliorate retiree pension cuts necessitated by the bankruptcy. With the bargain in place, Detroit city retirees voted to accept the pension cuts and the DIA was allowed to become an independent institution, owned by a charitable trust, forever protecting its masterpieces from being considered city-owned assets.
Oops, Detroit doesn’t own that art anymore. (Good thing, too.)
Detroit set up the precedent that public pension benefits, including those for current retirees, could be cut in Chapter 9 bankruptcy.
Many don’t want to see that again. And here’s the bit most don’t want to mention: Detroit pensions (on paper) were well-funded. (Let’s not talk about the 13th checks.)
There were issues with the Detroit pensions, but not to the extent of Chicago pensions. In a bankruptcy, you better believe Chicago pensions would be deeply cut. The reason is that a bankruptcy workout is approved only if the balance sheet and promises going forward are cleared and sustainable. (It need not be equitable, per se. Bondholders can be treated much worse than pensioners.) The bankruptcy judge doesn’t want to see your face in there again in 5 years.
Thing is… I don’t think Chicago… or Illinois can really be repaired with Chapter 9, either. They’re not ready for the level of honesty required for Chapter 9.
Yesterday, there were budget hearings for the Chicago Public Schools where there’s a $700 million hole in the proposed budget, and this is what the teachers union is saying:
20 July 2026, ABC 7: Chicago Public Schools holds public hearings on budget amid $700M shortfall [emphasis added]
On Monday, the district held a pair of public hearings on the spending plan which is already facing significant push back from the Chicago Teachers Union.
CPS may be in dire financial straits facing a $720 million deficit, but CPS CEO Dr. Macquline King said that well over half of the teachers that got laid off are expected to get offered new positions.
….
“We have 1,700 vacancies that are available for our teachers, and we expect about 65 to 85% of those teachers will find new homes,” King said.
During the public hearing, the teacher’s union continuing their messaging directly to board members.
“Our demands are simple: no cuts, no furloughs. This budget can’t be balanced at the expense of our students and professionals who nurture and care for our city’s children,” CTU Recording Secretary Vicky Kirzydlo said.
The pension funds I’m talking about don’t even include the education system.
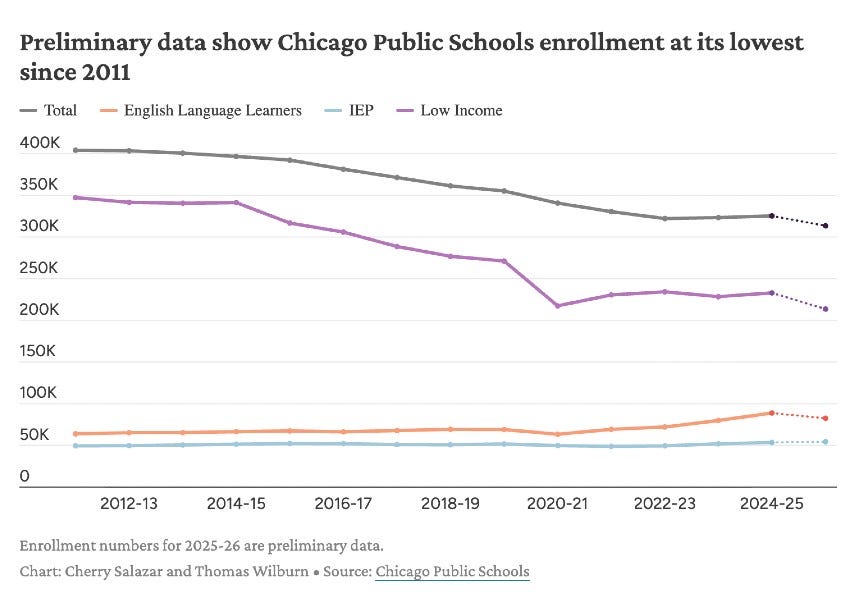
Given that Chicago has had a decreasing student population, and the kind of rhetoric the CTU keeps pumping out — and those are some very concrete numbers — they’re not ready for the abstract numbers involved in dealing with debt.
Let’s move on with other people’s comments.
Stu Loren: High Investment Returns on Too-Small Asset Amounts Doesn’t Do Much
17 July 2026, Chicago Tribune: Chicago’s pensions had a great year, but that won’t save them [emphasis added]
Chicago’s pension funds just had the kind of year that’s supposed to fix things. Returns came in between 11% and 14%. Contributions hit records, including $272 million in supplemental payments. And yet, according to the city’s annual financial report, our pension debt grew — up $500 million from what the city reported last year, to $36.4 billion. If a banner year cannot reduce that shortfall, it’s fair to ask whether this system is sustainable.
That said, there was some improvement. The funded ratio rose from 25.4% to 28.1%, driven by asset growth of 14%, while liabilities grew just 3%. The catch is scale: The funds hold only $14 billion of assets against $51 billion of liabilities.
At that size, more than $3 billion went just toward servicing existing obligations, consuming nearly every dollar the city and its employees paid in. Real progress belongs to the funding schedule: For example, the police fund is now on pace to hit its statutory funding target. But that schedule only works by growing the taxpayer’s bill every year for decades.
….
What the unions fail to understand is that financial reality eventually trumps legal reality because it bends legal reality to its will. The constitution can’t generate money from thin air. Only taxes can, and higher city taxes already have proved to be a political dead end — especially if there is no corresponding sacrifice from the public unions.
A union acting with foresight would come to the table now, while it can still shape bargaining terms, rather than risk taxpayers forcing the issue. Rhode Island’s unions negotiated and kept most of their position; Detroit’s litigated behind a pension clause much like ours and took court-imposed cuts anyway. A reasonable deal now beats a bad one later.
Chicago (and Illinois) have pushed the situation about as far as they can go.
They spent decades of deliberately underfunding pensions and overpromising, and that can go on for only so long. For Chicago, it’s gotten to the point that they’ve had to increase the contributions so rapidly just to cover current benefits.
They can barely increase those contributions to build up the funded ratio:
16 July 2026, Chicago Sun-Times: Chicago’s top mayoral aides pull back on promise to make second half of pension advance in full
The $16.7 billion budget approved by a City Council majority that rejected Mayor Brandon Johnson’s corporate head tax required the city to make a full $260 million advance pension payment to stave off another costly reduction in Chicago’s bond rating.
The Johnson administration ignored that mandate, made a half payment of $130 million in January, and promised to pay the other half in the second quarter of this year. Now that second installment is in jeopardy.
During a daylong Budget Committee hearing Thursday on the city’s midyear financial report, top mayoral aides said they are evaluating when and how much the city can afford to pay.
These problems were easy to foresee.
They’ve played games as long as they can, and it won’t take much to make the funded ratios erode once again. Some down years in the market, some years of underfunding, and here we go sliding down the asset death spiral where they have to liquidate current assets to meet current cash flows.
It won’t matter that Chicago can’t go to federal bankruptcy court. Chapter 9 is just a process — money can run out whether such a process exists.
Susan Mendoza: Candidate for Chicago Mayor on the Pensions
13 July 2026, WSJ editorial: Chicago’s Coming Pension ‘Pneumonia’ [link goes to Mendoza’s campaign site - emphasis from Mendoza’s site]
Maybe Chicago isn’t a lost cause. That’s the power of positive thinking about some surprising truth-telling about the city’s public pension mess from Illinois comptroller Susana Mendoza.
“If the [stock] market gets a cold,” Ms. Mendoza, a Democrat, said in a recent interview with the Financial Times, “I don’t even know that we’ll survive with pneumonia.” You might say that Chicago’s pension funds currently have the equivalent of walking pneumonia—sick, but not yet on a ventilator.
Last month Ms. Mendoza announced that she’ll run against Mayor Brandon Johnson if he runs for re-election next year. It’s nice to hear some honesty about the city’s perilous finances. Chicago’s pension funds were in aggregate only 28.1% funded last year—compared to a national average of 82.5%.
Nonetheless, Gov. JB Pritzker signed legislation last year that boosted pension benefits for younger Chicago police officer and firefighters. For context, Detroit’s pension funds were about 60% to 80% funded when the city filed for bankruptcy in 2013.
As Ms. Mendoza said, “you are in the area of near-insolvency at this funded level.” The lower a pension fund’s ratio, the harder it is to dig out of the hole even as taxpayers shovel out more and more money to keep the shortfall from growing. Chicago’s pension costs have doubled over the last six years and are the biggest driver of its budget deficits.
10 July 2026, FT: Years of low contributions in a city struggling with budget pressures have led to billions of dollars in unfunded liabilities [link goes to Mendoza’s site]
Chicago’s underfunded pension system is in dire condition, with some funds at risk of becoming “completely insolvent” in a market correction, Chicago mayoral candidate Susana Mendoza warned.
“If the market gets a cold,” Mendoza said in an interview with the FT, “I don’t even know that we’ll survive with pneumonia.”
….
Few US cities better exemplify the country’s public pension crisis than Chicago, whose retirement plans’ aggregate funded ratio has fallen by more than two-thirds since 2000.
….
Chicago’s pension crisis is emerging as a key issue in the city’s 2027 mayoral race, with candidates including US congressman Mike Quigley. While most of them have made the city’s fiscal challenge a central campaign issue, Mendoza has taken one of the strongest positions on pensions, arguing Chicago cannot afford further benefit enhancements that would pressure an already stretched system.
“Having something is certainly better than having 100 per cent of nothing,” she said. Mendoza acknowledged any overhaul of Chicago’s pension system would require difficult compromises.
“Realistically, how do we get these pension funds stabilised?” she said. “Everyone is going to potentially have to talk about sacrifice.”
Many of Chicago’s public workers reject that argument, saying they should not bear the cost of decades of pension underfunding by the government.
“The pension debt is caused by the failure of the city to pay what it owed in the past,” said Anders Lindall, a spokesperson for AFSCME Council 31, Illinois’ largest public employees’ union, “saying that you won’t talk about future benefits is actually not addressing the problem. That’s kind of a misdirection play”.
Mendoza also proposed expanding voluntary pension buyouts, allowing eligible workers to take lump-sum payments in exchange for giving up certain future benefits, while directing any surplus city revenues towards pension stabilisation and the city’s rainy-day fund.
“Anything and everything is on the table because we do have to stabilise the city’s finances,” she said.
I don’t think it’s fair to claim that Chicago exemplifies the country’s public pension problem. It’s the worst municipal pensions out there, in terms of fundedness. That’s not fair to the pension systems that have behaved properly… I can pick better systems (even NYC!) as examples. So let’s move on from there. (Same for Illinois).
Illinois and Chicago exemplify some of the worst situations for public pensions in the United States. Period.
11 June 2026, Fran Spielman Podcast at Chicago Sun-Times: The outgoing state Comptroller said the next mayor of Chicago needs to have a “come to Jesus moment” with union leaders and demand the concessions needed to prevent city employee pension funds from going bankrupt and dragging the city under. [link to Mendoza website]
“These continuing obligations with no ability to pay them is what drags the city into bankruptcy… It’s an absolute crisis of insolvency that we are just teetering on… When the market gets a cold, we’re not going to get pneumonia here — they will go insolvent,” she said of the four city employee pension funds.
When Mendoza (and others) talk about public pension insolvency, they mean running out of assets in the funds and having to operate in a pay-as-they-go manner.
This is not the same as an insurer going insolvent, which means the insurer doesn’t have enough assets to pay their promises (and have a little extra capital and surplus on top of that for safety).
This is why I talk about asset death spirals. This is how public pensions go insolvent — they have to cash out their assets due to insufficient contributions and insufficient investment returns. When they’re deeply underfunded and they hit a bad market, that’s what occurs.
As you see in the stories on Mendoza’s remarks, no, the public employees and retirees are not going to go softly into pension cuts. They do not understand that it does not matter whether they are to blame for pushing politicians to increase pension promises without increasing contributions. It does not matter who is to blame. Current taxpayers and voters do not care.
“But you promised” and “It’s not my fault” don’t mean much when the money runs out.
In Detroit, they did their best in the Grand Bargain, and still they had to cut pension benefits to those already retired. And their pensions had a better-funded position than Chicago.
To be sure, ALL THE OTHER CITY PENSIONS OUT THERE are better-funded than Chicago.
When the money runs out, and it is, you are not going to get 100% of the over-promised benefits because the benefits were not fully contributed for at the time the promises were made and earned. See how that works? THIS IS WHY YOU REQUIRE YOUR PENSIONS TO BE FUNDED.
Now, Mendoza is not going to be popular at all with the public employee unions. Duh. Rahm Emanuel was also not popular with those groups. He was not allowed to cut pension benefits either, due to the Illinois constitution:
May 2015: Illinois Pensions: How Did We Get Here? The 1970 Constitution
For convenience, this is what the text says:
SECTION 5. PENSION AND RETIREMENT RIGHTS
Membership in any pension or retirement system of the State, any unit of local government or school district, or any agency or instrumentality thereof, shall be an enforceable contractual relationship, the benefits of which shall not be diminished or impaired.
This is what needs to be changed before any of the pension benefits can be changed outside of federal bankruptcy court (yes, you just try the federal courts with this).
So get cracking on amending the state constitution.
More Links on Chicago Pensions
21 July 2026, A City That Works: A 2026 update on the State of Chicago Pensions

9 July 2026, A City That Works: How the next mayor should think about pensions
15 July 2026, Wirepoints: Wirepoints’ Mark Glennon with Mike Koolidge on AM560: Chicago’s Pension Crisis Deepens as Property Taxes Fund Fewer Public Services
20 July 2026, WTTW: Chicago Alderpeople React to City’s $89M Budget Shortfall, Debate Debt Collection
Older Chicago Pension Links
Mar 2026: Chicago Pensions Watch: DROP Will Not Save the Pensions
Nov 2025: How Pension Promises Fail: Examples in Christian Brothers Services and Chicago Pensions
Sep 2025: Podcast — Chicago Pensions: The $11 Billion Sweetener, POBs, and the Road to Insolvency
Jan 2025: Geeking Out: Picking Apart a Chicago Pension Actuarial Report from 2024
Jan 2024: Oh Woe, Chicago: How Will the Pensions Flow?
July 2023: Chicago Pensions: Drowning, Not Waving
May 2025: Did New Chicago Mayor Brandon Johnson Inherit The Worst City Pensions in the Country? [answer: YES]
Feb 2023: Podcast — Chicago Mayoral Race: Good Luck Dealing With the Pensions
Glad there is no bandwagon for Chapter 9 authority in Illinois. My town, Skokie, AA+ bond rating does not need Chapter 9 and its adoption would likely raise interest rates for all towns given that it adds a risk to the bond purchaser. Dan